
If you are getting ready to buy a home in Pennsylvania, one of the first questions on your mind is probably timing. Sellers want to know you are serious, real estate agents will not usually walk you through a house without one, and you want to know your budget before you fall in love with a place you cannot afford. Preapproval is the piece that answers all three. But how long does it actually take, and what can slow it down or speed it up?
The short answer: same day to a few days
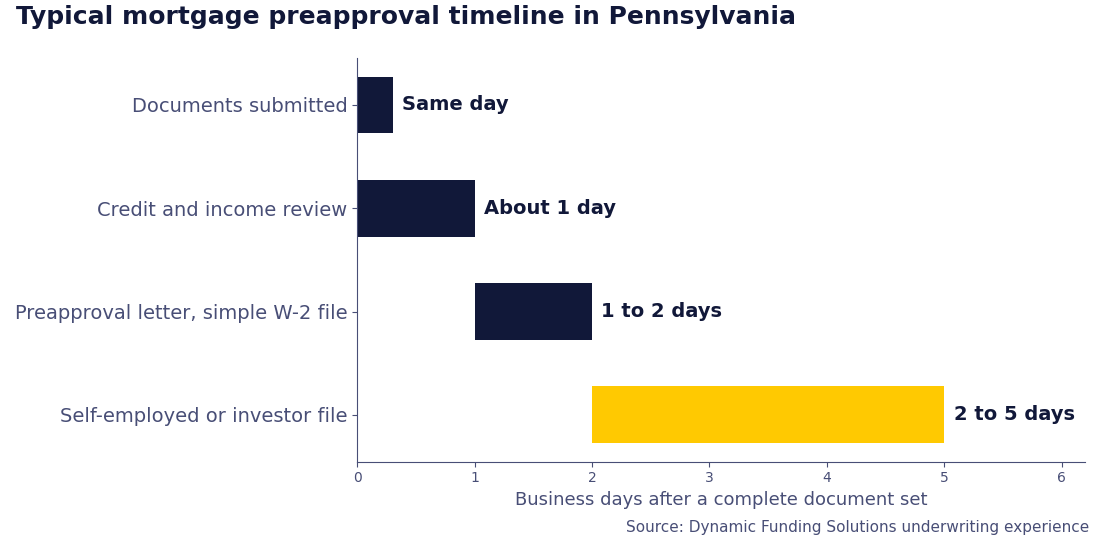
For most borrowers with straightforward, well-organized finances, a mortgage preapproval in Pennsylvania can be turned around the same day or within a day or two once all the paperwork is in hand. The actual review of your income, assets, and credit does not take long on its own. What extends the timeline in practice is usually the back and forth of gathering documents, not the underwriting itself.
For self-employed borrowers, real estate investors, or anyone with more complex income, the timeline can run a bit longer because there is more to review and sometimes alternative documentation to use, such as bank statements instead of tax returns. Our bank statement mortgage loan programs exist specifically for this situation.
What preapproval actually involves
Preapproval is a review of your financial picture that results in a letter stating how much you are likely qualified to borrow, based on documentation you provide and a credit check. It typically involves a credit pull, verification of income, a look at your assets for down payment and reserves, and a review of existing debts to calculate your debt-to-income ratio. This is different from prequalification, which is a quicker, less verified estimate based mostly on what you tell the lender rather than documentation.
Documents that speed things up
The single biggest factor in how fast preapproval moves is how quickly and completely you can provide documentation. Recent pay stubs, W-2s or 1099s from the last two years, tax returns, and bank statements showing your down payment and reserve funds all help. If your income is not a simple W-2, our page on 1099 mortgage options walks through what that looks like for contract and freelance income.
Why self-employed and investor borrowers sometimes take longer
Self-employed borrowers and real estate investors often have income that does not fit neatly into a pay stub and W-2 format. Tax returns for business owners can include deductions that reduce taxable income on paper, even when actual cash flow supports a larger mortgage. Real estate investors evaluating a vacation rental or short-term rental property also go through a slightly different review since rental income projections come into play; our page on DSCR loans for investment property covers what lenders typically want to see.
Credit issues and how they affect the timeline
Credit history plays a real role in how smoothly preapproval moves. If your credit report has errors, old collections, or accounts that need clarification, those items can require extra explanation, which adds time. It is worth pulling your own credit report before you apply. The Consumer Financial Protection Bureau has guidance on checking and understanding your credit report at consumerfinance.gov.
How working directly with your lender changes the timeline
At a large call center lender, your file can pass through several hands before anyone with authority to answer a real question looks at it. Dynamic Funding Solutions is owner-operated, which means the people reviewing your file and answering your questions are the same people working your loan from start to finish. This removes a lot of the delay that comes from communication getting lost between departments.
What can slow preapproval down
A few common issues tend to stretch out the timeline: missing or incomplete documentation, recent large deposits that need to be sourced and explained, multiple income sources that each require separate verification, credit report items that need clarification, and slow response time once documents are requested. None of these mean preapproval will not happen; they just mean it may take a few extra days.
Our experience working with Pennsylvania and Florida borrowers
Dynamic Funding Solutions works with home buyers, homeowners, self-employed borrowers, and real estate investors across Pennsylvania and Florida from our office in Huntingdon Valley, Pennsylvania. Standard documentation loans, asset depletion programs, and non-QM options all come through the same team, so there is no learning curve when your situation does not fit a conventional mold.

How to get preapproved faster
Most of the time saved in preapproval is saved before you apply. Three steps make the biggest difference.
- Know your budget first. Run your numbers in our free mortgage calculators to see the monthly payment and the price range your income supports. You will know which loan programs to ask about before the first call.
- Gather your documents in one place. Our mortgage paperwork checklist lists what lenders ask for, with separate columns for W-2 employees, self-employed borrowers and investors. Sending a complete set on day one avoids the back and forth that adds days.
- Answer requests the same day. When the underwriter asks for a letter of explanation or an updated statement, a quick reply keeps your file at the top of the pile.
If anything in your file is unusual, such as a recent job change, a large deposit or income from your own business, tell your loan originator at the start. Raising it early lets the right program be chosen up front instead of halfway through.
Frequently asked questions
How long does mortgage preapproval take in Pennsylvania?
For borrowers with complete, straightforward documentation, preapproval can often be completed the same day or within a day or two. Self-employed borrowers or those with more complex income may take a bit longer since there is more documentation to review.
What is the difference between prequalification and preapproval?
Prequalification is a quick estimate based on information you self-report, without full verification. Preapproval involves an actual review of your credit, income documentation, and assets, which is why it carries more weight with sellers and real estate agents.
Does preapproval take longer for self-employed borrowers?
It can, mainly because self-employed income often requires additional documentation, such as tax returns or bank statements, rather than a simple pay stub and W-2. Programs designed specifically for self-employed borrowers help streamline this review.
What documents should I have ready before applying for preapproval?
Recent pay stubs, W-2s or 1099s from the last two years, tax returns, bank statements showing your down payment and reserves, and identification. Having these ready before you start tends to shorten the process considerably.
Talk to a Pennsylvania mortgage originator
Call Dynamic Funding Solutions at (215) 364-7171 or send your details and a licensed originator will tell you what your preapproval timeline looks like.